myFICO - Credit Score Tracking

Screenshots
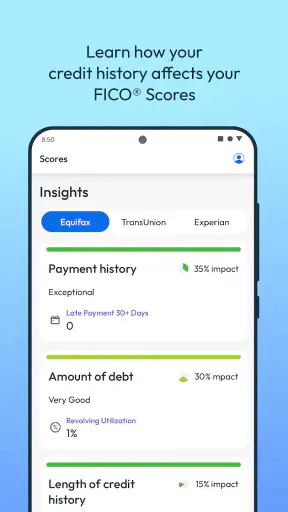
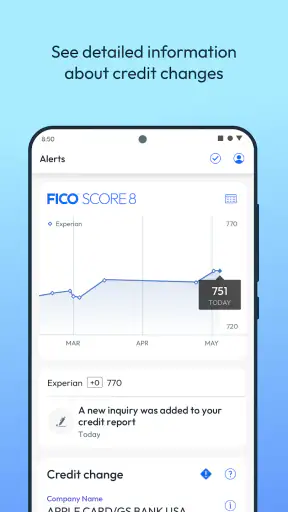
Details
- Rating
- 4.47K reviews
- Version
- 4.0.23.4
- Developer
- FICO
Analysis by Norviv
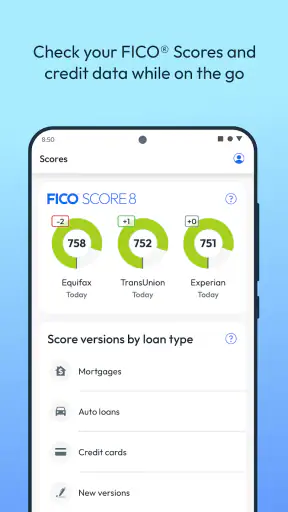
When a credit decision is close, I would rather check a familiar score than guess from a vague financial app. That is where myFICO fits for me: it is a free finance app from FICO focused on viewing a FICO Score and an Equifax credit report for situations such as credit cards, mortgages, and loans. I found it most useful as a personal reference point, not as a complete household budgeting system or a replacement for careful review of every account.
The app has a clear purpose, and that narrow focus is part of its appeal. Instead of trying to combine spending trackers, bank accounts, investment dashboards, and bill reminders, it puts attention on credit information. That makes it easier to open when I am preparing for a major application or simply trying to understand where my credit position stands. The trade-off is equally clear: anyone expecting a full financial command center will need other tools alongside it.
How myFICO Works in a Shared Household
When a household shares financial goals, I find it helpful to separate the conversation from the account itself. One person can review their own credit information privately, then share the specific takeaway the household needs—such as whether a report entry needs checking—without turning a personal report into a shared document. That boundary keeps planning practical while respecting whose credit history is actually being viewed.
A realistic shared-device situation
Imagine a couple using the same tablet at home. One person is preparing to apply for a mortgage, while the other is monitoring credit before changing cards. The device may be shared, but the credit information should not be treated as shared household content. I would use myFICO as an individual account tool, opening it for the person whose score and report are being reviewed and then signing out or handing the device back only after checking that the account view is closed.
This matters because a credit report is more sensitive than a normal shopping or weather app screen. A household can coordinate around a financial goal without everyone having access to each other’s personal credit details. In practice, I would discuss the result—such as whether an application should wait—rather than pass the phone around while the report remains visible.
The app can be useful in that conversation because it gives the household a common starting point. If one person is worried about applying too soon and another assumes everything is fine, looking at the relevant FICO information together can replace guesswork with a more grounded discussion. I would still keep the account owner in control of the login and avoid saving credentials on a device that guests or children regularly use.
Setting boundaries before the first check
My first recommendation is to decide whose account is being used before installing or opening the app. The developer is FICO, so the product naturally centers on personal credit information rather than a shared family profile. I would not create a casual “household” login just to make coordination easier. Credit histories belong to individuals, and mixing identities can make an already confusing financial conversation worse.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Setup is also a good moment to agree on what the app will and will not be used for. I would use it to inspect the available score and Equifax report, identify information that deserves attention, and prepare questions before contacting a lender or creditor. I would not treat it as proof that a lender will approve an application, because a displayed score is one part of a decision that can involve income, debt, documentation, and the lender’s own criteria.
For a shared device, I would keep a simple routine: the account owner opens the app, checks the information, closes the session, and avoids leaving report pages in the recent-apps view. That is not an elaborate family-management feature; it is just sensible handling of personal financial data. If the device belongs only to one adult, the routine is easier, but the same boundary still makes sense.
Coordinating a household decision
The strongest everyday use case I found is preparation. Suppose we are planning to apply for a new credit card after paying down balances. I would check myFICO before submitting anything, compare what I see with the information I already know, and then decide whether the timing deserves more research. The app helps turn “I think my credit is okay” into a more specific conversation about the report and the score.
For a mortgage or loan discussion, I would use the app as a checklist starter. I could review the report for unfamiliar entries, note questions, and gather documents separately. That separation is important: myFICO can help me notice what needs attention, but it does not remove the work of verifying details with the relevant creditor or lender.
A useful household habit is to avoid making a major application immediately after a quick glance. I would record the date of the check privately, write down any issue that needs clarification, and allow time to investigate before acting. This is especially helpful when two people are coordinating finances but only one person’s credit profile is being viewed. The household can agree on the next step without assuming both profiles are identical.
Another practical trade-off is that the app is better for credit-focused conversations than for tracking shared spending. If the real question is “How much did we spend on groceries this month?” I would choose a budgeting or banking tool instead. If the question is “What does my FICO-based credit picture look like before I apply?” this is much closer to the right tool.
What the report view is good for
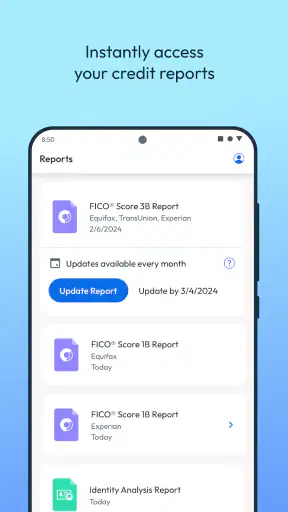
The Equifax report is more useful to me when I read it slowly rather than treating it as a single health score. A score can attract all the attention, but the report gives context about the information behind it. I would look for accounts or inquiries I do not recognize, check whether personal details appear consistent, and mark anything that needs follow-up. The app becomes more valuable when I use it to generate questions instead of simply waiting for a number to reassure me.
This is one of the less obvious strengths of a dedicated credit app: it can create a repeatable review habit. I might check before a planned application, after a significant change in my credit situation, or when something on a statement does not make sense. I would avoid compulsive checking, though. Frequent viewing does not automatically improve a score, and the app should support decisions rather than become a source of daily anxiety.
I also would not assume that every score seen elsewhere will match the one shown here. Credit products can use different scoring models, data sources, and update timing. That means myFICO is valuable when I want to understand the FICO-oriented view presented through its Equifax report, but I would not compare a number from another service as if both were guaranteed to be the same measurement.
Age, trust, and personal access
The content rating is Everyone, but that does not make the app a children’s finance tool. The subject matter is personal credit, and meaningful use generally belongs with the adult who owns the financial profile. I would not hand it to a child as a learning game, nor would I let a young household member explore an adult’s account simply because the app itself carries an Everyone label.
For teenagers learning about credit, I would explain the ideas separately and demonstrate only information that the account owner is comfortable sharing. The app can support an adult’s preparation and education, but it should not be mistaken for a supervised family dashboard. I found no reason to treat the presence of the app on a shared device as permission for everyone in the home to inspect its contents.
Trust also matters between adults. A couple may manage bills together while keeping individual credit histories private. That is a reasonable boundary, not a sign that household finances are being ignored. I would decide in advance whether the account owner wants to share the score, discuss report entries, or simply report a conclusion such as “I need to investigate something before applying.” myFICO works within that arrangement, but it does not replace the conversation about consent.
Account separation is more important than convenience
If two adults both want to use the app, I would keep their use separate rather than switching casually between accounts. The convenience of one shared login is not worth the risk of confusing whose report is open or whose credentials are stored. On a personal phone, that may be straightforward. On a family tablet, I would be more deliberate about locking the device and closing the app after use.
I would also avoid taking screenshots of report pages for a group chat or leaving them in a shared photo library. Coordination should happen through selected facts and agreed actions, not by spreading sensitive pages across devices. This is a workflow decision rather than a feature claim, but it makes a noticeable difference in a household where privacy expectations vary.
Where the app fits among alternatives
Many banking apps show a credit score as one tile among balances, transactions, and card offers. That can be convenient if I only want a quick glance while checking my account. myFICO makes more sense when the credit score and Equifax report are the main reason I opened the app. Its focus feels less distracting, especially before a loan or card decision.
On the other hand, a bank app may be better for monitoring spending, moving money, or reviewing recent transactions. A general credit-monitoring service may also suit someone who wants broader identity or alert-oriented coverage, depending on that service’s design. I would choose myFICO when I value the FICO and Equifax pairing, and choose a broader financial app when I need one place for daily money management.
The free price makes trying it less intimidating, but “free” should not be interpreted as a promise that every possible credit-related service is included. I would read each screen carefully and distinguish the information available in the app from any separate product or service that might be presented around it. That habit is useful with all finance apps, particularly when the user is already thinking about borrowing.
Performance, maturity, and practical expectations
The app was released on August 18, 2015, and its current version is 4.0.23.4. That history gives it the feel of an established credit product rather than a newly launched experiment. I used it with the expectation that the important value would be the clarity of the credit information, not entertainment or extensive customization.
It requires at least iOS or Android version 12, so I would check the operating system on an older household phone or tablet before planning to use it there. This is an easy detail to overlook when a family device is shared for years. If the device is below that requirement, updating it or choosing a newer device becomes part of the setup decision.
The app is free and has passed the one-million-install mark, with an average rating of 4.3 from roughly twelve thousand ratings and about four and a half thousand written reviews. Those figures suggest that it has a substantial user base and generally positive reception, but I would still judge it by the specific task I need it to perform. Popularity cannot tell me whether it is the right fit for a household that wants budgeting, joint account management, or detailed credit education.
Limitations I would consider before relying on it
The biggest limitation is scope. A score and report are useful, but they do not answer every question that comes before borrowing. I still need to understand the terms of a card or loan, estimate whether the payment fits the household budget, and confirm questionable report information through the proper channels. If I wanted automatic expense categorization or a shared bill calendar, I would add another tool rather than expecting myFICO to cover it.
The second limitation is interpretation. A number can look authoritative and still be misunderstood. I would not use a small change as a reason to panic, and I would not treat a comfortable-looking score as a guarantee of approval. The report deserves attention, and the lender’s evaluation may use information or criteria that are not represented by the screen I am viewing.
There is also a human limitation: shared use can create pressure. One partner may want to inspect everything, while the account owner may prefer privacy. The app cannot solve that disagreement. Its responsible use depends on clear permission, separate credentials, and an agreement about what information will be discussed.
Who should use it and who should skip it
I would recommend myFICO to an adult who wants a focused way to review a FICO Score and Equifax credit report, especially before thinking about credit cards, a mortgage, or a loan. It is also a sensible choice for a household that wants one person to prepare a credit update and then discuss the relevant conclusions with a partner.
I would skip it as a primary tool if my main goal were shared budgeting, transaction tracking, investment management, or bill coordination. I would also avoid making it the center of a child-focused financial setup. For those situations, a different category of app would be more appropriate, with myFICO used only when an adult needs its specific credit information.
My overall household verdict is positive but carefully defined. I like the focused purpose, the connection between the FICO Score and Equifax report, and the way it can make a pre-application conversation more concrete. I would use it on an individual account, keep access private, and treat its information as a decision aid rather than a promise about what a lender will do.
For me, the best workflow is simple: the account owner checks the report, notes anything unclear, discusses only the necessary conclusions, and uses other tools for budgeting or joint money management. With those boundaries, the free app is a practical addition to a household’s financial routine. Without them, the shared-device convenience can create more privacy risk and confusion than value.
Frequently Asked Questions
01What is myFICO – Credit Score Tracking used for?
myFICO is designed to help users monitor and understand their credit information, particularly FICO® Scores, which are widely used by lenders when evaluating credit applications. The app can provide access to score updates, credit reports, score explanations, and monitoring tools, depending on the subscription or service connected to your account. It is primarily useful for tracking changes and learning what may influence your creditworthiness.
02Does myFICO provide the same credit score that lenders see?
myFICO focuses on FICO® Scores rather than generic educational scores offered by some other services. However, lenders may use different FICO Score versions, credit bureau data, and industry-specific scoring models depending on the type of application. Therefore, the score displayed in the app can be highly informative, but it may not exactly match the score used by a particular bank, credit-card issuer, mortgage provider, or auto lender.
03Is myFICO free to download and use?
The myFICO app may be downloaded without an upfront charge, but many of its most valuable features require a paid plan, purchase, or an eligible myFICO service. Pricing and included benefits can vary by subscription level, such as the number of credit bureaus monitored, report access, update frequency, and identity-monitoring tools. Before subscribing, review the current terms, renewal conditions, and cancellation policy shown in the app.
04Does myFICO affect my credit score when I check it?
Checking your own credit information through myFICO is generally considered a soft inquiry and should not lower your credit score. It is different from applying for a loan or credit card, where a lender may perform a hard inquiry. Even so, users should remember that score monitoring does not prevent lenders from making their own checks, and the app cannot guarantee approval or a specific result for any future application.
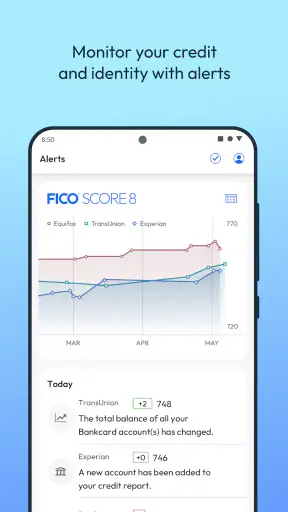
05Can myFICO help me identify identity theft or credit-report errors?
myFICO can help users notice unusual changes, unfamiliar accounts, new inquiries, or other activity that may deserve investigation, especially when monitoring features are enabled. It is not a replacement for carefully reviewing complete credit reports or contacting the relevant credit bureau and financial institution. If you find suspicious information, act promptly by reporting it, securing affected accounts, and following official identity-theft recovery guidance.


